One year on, Krugman concedes

“Due to the sizeable bear market rally that began in March 2009, many, if not most, economic observers are presently convinced that the global economic difficulties of last autumn are largely behind us now, courtesy of the aggressive, expansionary actions of the monetary and political authorities. They are wrong. It is not over. It has only begun. I believe that what we have witnessed to date is merely the first act in what will eventually be recognized as another Great Depression.”
– Vox Day, The Return of the Great Depression, June 29, 2009

“We are now, I fear, in the early stages of a third depression. It will probably look more like the Long Depression than the much more severe Great Depression. But the cost — to the world economy and, above all, to the millions of lives blighted by the absence of jobs — will nonetheless be immense.”
– Paul Krugman, The Third Depression, June 28, 2010

It looks like my predictions are running a little ahead of schedule again. RGD readers will recall that I didn’t have the mainstream economists starting to whisper about the possibility of a Great Depression 2.0 until the end of 2010. This is supposed to be the time for talking Double-Dip and W-shaped Recovery. But then, Krugman has always been rather more dyspeptic than the rest of his colleagues. I await with interest for all of those who said that my forecast was incorrect because I dared to contradict a FAMOUS ACADEMIC and NOBEL-PRIZE WINNER to explain this mysterious failure of credentialism.

Krugman is wrong about the historical use of the term depression, of course, (depression was synonymous with recession until after the Great Depression ended), just as he is wrong about the reason the global economy is sliding further into contraction. Fame and credentials are no substitute for the knowledge of history combined with a reliable theoretical model. Longtime readers who are investors may recall that my 2002 recommendation to buy gold and avoid real estate has worked out just a little better than Krugman’s 2002 recommendation to buy real estate and avoid gold.


WND column

Winning the War Against Men

There is a relentless war being waged against American men that literally spans the entire extent of their lives. From the womb, in which a woman’s “right” to abort a male baby for being male is defended but a similar right to abort a female baby for being female is vehemently opposed, to the grave, wherein the disparate impact of old age is ignored despite women living 5.2 years longer than men on the average, men are systematically, structurally and unstintingly under assault.

Most men understand this on some level, but like the nice dependable man who can’t figure out why attractive women repeatedly reject him in favor of unemployed losers with criminal records, they are incapable of doing anything about it because they simply can’t believe that women truly do not think or behave like men. Because they want to believe that women are “the civilizing force,” their “better halves” or “the fair sex,” they are constitutionally incapable of seeing what is, from a rational male perspective, the seething cauldron of amoral solipsism behind the collective pretty face.


Alpha disease

The divergent rate with which venereal disease affects the sexes is evidence in support of the Game perspective in which larger numbers of women are attracted to a smaller group of men:

About 16 percent of Americans between the ages of 14 and 49 are infected with genital herpes, making it one of the most common sexually transmitted diseases, U.S. health officials said on Tuesday… women were nearly twice likely as men to be infected, according to an analysis by the U.S. Centers for Disease Control and Prevention. About 21 percent of women were infected with genital herpes, compared to only 11.5 percent of men.

I wouldn’t trust the politically correct explanations attempting to explain away the gargantuan difference in black and white infection rates. Of course, as with illegitimate births, we can expect the white infection rate to eventually rise to approach the black level as white society increasingly mimics matriarchal black society.


That was a goal!

Great game between England and Germany, well-worth the overwrought build-up. Germany is slashing through the English defense, but England was brutally robbed of a very clear goal by Lampard that was remniscent of the 1966 game-winner. I didn’t expect England to give Germany this much of a game, but it’s a really good one although without a solid performance by David James Germany would be leading 4-2… assuming that FIFA would stop disallowing goals scored.

More about the first round games later. The US loss was disappointing, but they played okay and Ghana well-merited the win.


The Atlanta Journal/Constitution of Econ

It’s illuminating to see what small readerships are possessed by the most popular economics blogs. Because I read Mike Shedlock and Calculated Risk, I always assumed that a number of the long list of blogs on their blogrolls were similarly well patronized. But apparently that’s not so much the case, although the omission of sites like Karl Denninger’s Market Ticker indicates that around half of the bigger fish are missing from this survey. But if EconDirectory’s list of top economics blogs is to be trusted, then this would appear to be the 11th most trafficked economics-related blog, in between #10 VoxEU’s 12,405 daily pageviews and #11 TaxProfs 8,041. It’s the same when it comes to visits, although if one adds the 1,400 feed readers – this is one of the few blogs to provide full-text feeds that negate the need to come here to read the posts – that would bump VP up to #9.

This is both scary and heartening. It’s scary, because if even the most popular econ blog only attracts 56k daily readers, it’s not hard to understand the level of economic ignorance on the part of the elite and the electorate alike. And it’s heartening, because this indicates it is feasible to reach a substantial percentage of the people who are sufficiently interested in the subject to follow it.

While we’re on the subject, it’s interesting to note that the Wall Street Journal has finally begun to wake up to the intellectual bankruptcy of the Neo-Keynesian response to the initial stages of the Great Depression 2.0:

Today’s G-20 meeting has been advertised as a showdown between the U.S. and Europe over more spending “stimulus,” and so it is. But the larger story is the end of the neo-Keynesian economic moment, and perhaps the start of a healthier policy turn. For going on three years, the developed world’s economic policy has been dominated by the revival of the old idea that vast amounts of public spending could prevent deflation, cure a recession, and ignite a new era of government-led prosperity. It hasn’t turned out that way….

Like many bad ideas, the current Keynesian revival began under George W. Bush. Larry Summers, then a private economist, told Congress that a “timely, targeted and temporary” spending program of $150 billion was urgently needed to boost consumer “demand.” Democrats who had retaken Congress adopted the idea—they love an excuse to spend—and the politically tapped-out Mr. Bush went along with $168 billion in spending and one-time tax rebates.

The cash did produce a statistical blip in GDP growth in mid-2008, but it didn’t stop the financial panic and second phase of recession. So enter Stimulus II, with Mr. Summers again leading the intellectual charge, this time as President Obama’s adviser and this time suggesting upwards of $500 billion. When Congress was done two months later, in February 2009, the amount was $862 billion. A pair of White House economists famously promised that this spending would keep the unemployment rate below 8%. Seventeen months later, and despite historically easy monetary policy for that entire period, the jobless rate is still 9.7%….

The response at the White House and among Congressional leaders has been . . . Stimulus III. While talking about the need for “fiscal discipline” some time in the future, President Obama wants more spending today to again boost “demand.” Thirty months after Mr. Summers won his first victory, we are back at the same policy stand.

RGD readers may recall that I predicted not only the failure of Stimulus II, but the failures of Stimuli III and IV as well. I expect they’ll finally give up on the fruitless endeavor sometime between V and VII. The problem, which even the new-found Neo-Keynesian skeptics don’t understand, is that these failed stimulus packages not only haven’t worked, but they are going to exacerbate the next phase of the contraction that is even now gathering steam. Although they appear to have a glimmer of concern in that regard; consider how the WSJ is ineptly attempting to construct an ex post facto cover for its backside.

“With the economy in recession in 2008 and 2009, we argued that some stimulus was justified and an increase in the deficit was understandable and inevitable. However, we also argued that permanent tax cuts aimed at marginal individual and corporate tax rates would have done far more to revive animal spirits, and in our view would have led to a far more robust recovery.”

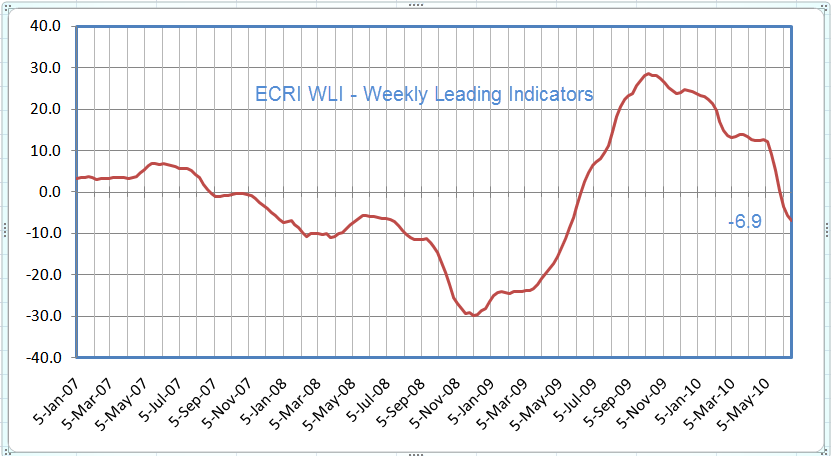
In other words, the WSJ still subscribes to the very economic idiocy they are describing as a dead end. It’s not that the magical incantation doesn’t work, it merely wasn’t chanted in precisely the correct manner prescribed in the Keynesian grimoire. This means that we can confidently expect the decision-making elite to continue digging and making the hole deeper as the situation worsens. Note that the average weekly leading indicators are now at -6.9, a decline last seen in July 2008.

Early adopters only

FYI: the online store is now open, but since we’re starting to ship the first preorders on Monday, we’re replacing the promised pre-order discount with a 20% early adopter discount that is valid until July 4th. We have already sold nearly half our initial production run, so don’t hesitate to order if you’re interested getting your hands on “The King of All Computer Mice” and its 3,072 simultaneous commands.


Hypergamy trumps ideology

Even stark raving feminists go on the hunt for gamma providers… once they begin to feel their looks starting to fade. The perceptive observer will note the Game-predicted pattern at work in Jessica Wakeman’s unexpected feminist defense of gold-digging:

Take me, for instance. I’m afraid I’m going to get tarred and feathered as a “bad feminist” for admitting this, but yeah, I do want to marry someone who can financially support both me and our kids…. Right now, I rent an apartment with my boyfriend and a roommate, but personally, I’m still living at the edge of my own means as it is. I don’t make a lot of money as a journalist, I owe lots of money to student loans and unless my future husband or I had a great job prospect someplace else, I don’t want to live very far outside New York City, because that’s where the media capital of the world is right now.

Maybe this isn’t “feminist,” but logically, I need to marry a guy who makes more money than I do—preferably a lot more money than I do—for us to be able to afford what I want and I hope he will want, too. An apartment big enough for kids, prenatal care, doctors appointments, birthday presents, vacations, summer camp, college, their own car, all that stuff. I know parents can raise children well on much less. But personally, that’s not the lifestyle I grew up with. I want to be able to give my children everything I had—maybe a little less, maybe a little more—because I think my parents did a great job.

I also would immediately disqualify entering into a sharing-bank-accounts relationship with a man who proved to be irresponsible with his cash. College loan debt is fine (I’ve got it) and a reasonable balance on the credit card debt is understandable (I’ve got that, too). But I couldn’t wrap up my life or my children’s lives around someone who spent or managed money irresponsibly.

So, the woman is living with her current boyfriend while simultaneously seeking some unwitting gamma who will completely fail to see that his only attraction for her is to pay her bills… and of course, her debts. This fits the classic pattern wherein a woman devotes her prime years to “having fun”, which translates as having as much sex as possible with alphas and unemployed artists while ignoring the nice deltas and gammas who helplessly offer her the promise of a stable relationship.

Then, once the daunting specter of THIRTY looms on the horizion, she begins to lower her sights and transform her attentions to the provider class of men further down the socio-sexual hierarchy. And this is why most married sex lives will tend to dry up after a year or two; the woman is no longer required to fake her level of sexual interest in the benefit of the hapless provider and there is nothing he can do about it since she has the full force of the feminized law at her disposal.

This is why it is a very risky and probably foolish endeavor for men to marry women over the age of 25. Even an extended “try before you buy” approach is unlikely to improve your odds, as observation suggests that desperation and/or determination to entrap a provider causes women to present a false sexual front for an extended period of time. And worse, over time her hypergamous nature is going to rise to the forefront and cause her to return to her “happiness-seeking” (read: alpha-seeking) habits.

There are two ways to address the situation. One is to marry a genuinely religious or submissive woman, as she will have a strong inherent resistance to her hypergamous instincts. Remember, instinct is merely an influence, it is not a controlling factor. The second, of course, is to not marry at all. But whatever you do, do not even speculate about the possibility of considering the thought of marrying an aging, debt-laden feminist who is scouting about for a long-term delta provider following an extended ride on the thugacious carousel.


Kagan not kosher

I’m not sure, but I think the rabbis just called her a pig:

Supreme Court nominee Elena Kagan is “not kosher” — meaning she is not fit to serve on the court — according to more than 850 Orthodox members of the Rabbinical Alliance of America. That’s the term the rabbis used about Kagan in a press release issued Thursday, saying “Elena Kagan is not kosher. She is not fit to sit on this Court — or any court.”

Rabbi Yehuda Levin, spokesman for the alliance, told CNSNews.com on Thursday that “a great deal has been made about the fact that she would be the second Jewish woman on the court, and we want to signal to people across the country that we take no pride in this.”

I can’t muster much concern about Kagan one way or the other. I mean, the only surprise was that she wasn’t black. I was expecting Obama to appoint a black Marxist lesbian, so the fact that he went with a Jewish one instead doesn’t fill me with alarm. It’s not like the Supreme Court matters anymore, it’s about as relevant as the Imperial Roman Senate.


More extend and pretend

These so-called financial reforms will do absolutely nothing to bring the nation out of the financial crisis and economic contraction. It doesn’t address outstanding debt, it doesn’t address mark-to-fantasy, it doesn’t address bank insolvency, and it doesn’t even slow down the increasing amount of bank fraud. It’s merely yet another attempt to protect the banks while deceiving the public into thinking that the government reining them in:

President Barack Obama declared victory Friday after congressional negotiators reached a dawn agreement on a sweeping overhaul of rules overseeing Wall Street….

One financial analyst, Richard Bove of Rochdale Research, said he believed the measure would have little impact because banks would find ways to hit consumers with more fees. “The good things coming out of this bill is virtually zero,” he said. “Did it help the U.S. economy? Did it solve any problems? The answer is no and no.”

Financial stocks rose in early trading Friday, as traders were relieved that banks would be allowed to continue most kinds of transactions. JPMorgan Chase & Co. rose 2 percent, while Citigroup Inc. climbed 2.1 percent.

Translation: the casino remains open.


Lessons from Greek history

This is neither the first nor fourth time that Greece has faced a serious default situation. But, as Michael Pettis of China Financial Markets explains, because so many different things have happened before, the question is less whether history will prove a guide to the future, but rather which historical example will prove to be the relevant one:

The economic recovery in the countries hit by crisis will not begin until they are recognized as insolvent and receive debt forgiveness from their creditors. Preceding every sovereign default is the fiction that the creditor country is simply facing a short-term financing problem, and that with a lot of discipline and a little bit of good will it will be able to work its way out of the crisis. During this period a number of restructuring “solutions” are proposed – all of which involve increasing debt, and often in the most financially destabilising way – which inevitably make the final resolution of the crisis much more difficult and which sharply raise financial distress costs. The most notorious recent example of these terrible “solutions” was Argentina’s disastrous debt swap in 2001, in which it dramatically increased the country’s total obligations while it desperately tried to maintain the fiction that it could somehow grow its way out of its impossible debt burden.

Greece, and probably two or three other countries, simply cannot repay their outstanding debt amounts. Ultimately they are going to default, and then in the restructuring process they will receive enough debt forgiveness that allows them to return to a sound footing and with a reasonable repayment prospect. But as long as they maintain the pretence that they can and will repay the full outstanding amount, and struggle with the burden, the resulting distortions in the economy will mean that businesses will disinvest and the country will not grow.

Historical precedence makes it clear that as long as the sovereign borrower is forced to struggle with an unrepayable debt burden, it will not grow. Eventually, as has happened in nearly every previous case, creditors and borrowers will acknowledge reality and will work out a debt forgiveness plan that will allow the economy to return to growth. Until then, expect weak growth, high unemployment, and constant battles over debt.

Although most US-based economists are convinced that the special status of the dollar somehow renders the USA impervious to economic laws, the danger of US debt default is nearly as great as it is in Europe. The fact that the defaults are likely to begin in the next two years with the state and local governments does not mean that they are going to end there. However, a partial default would be much more likely than a general one, with the USA defaulting on the third of its debt that is presently held by China coming as a prelude to war between the waning superpower and its self-appointed would-be successor.

Major economic and historical transition points are almost always accompanied by large-scale war. I see no reason to believe that this will not be the case again in this repetition of the cycle.